JBS, and the two per cent that is the whole business
What a spread board for JBS, built on AstratoFor the plant controller and the commercial teamProblem the margin was decided in three systems on three clocks, and nobody saw it whole until a lot closed
A reporting layer for a company that turns over BRL 417bn and keeps about 2.3% of it, where the margin is decided in three places that could not see each other.
16 min read · 9 min skimmed
Three clocks procurement, plant and market, none of them aligned. Drag one.
A reconstruction. The engagement was real and delivered on Astrato; the company figures are public, the data in the product is fictional, and no outcome is claimed.
Follow a lot from the pen to the port, then pull a destination’s export approval and watch a third of it re-route to the domestic market at a lower index.THE PRODUCT, NOT A PICTURE
Accessibility: The spread board passes axe-core’s WCAG 2.1 AA rules at desk and phone, in both settings, and in the 9 states this file links into. Not yet tried with a screen reader. The statement
Weight on a first visit: 383 KB of script and 13 KB of style, compressed, against budgets of 400 and 15 KB. The build fails if a product passes its budget. React Flow is in the first visit, because the lot’s flow is the first screen.
The states around it, each one a link: the warehouse not answering and a lot search that finds nothing. Each says what is true, names the next step and offers one action.


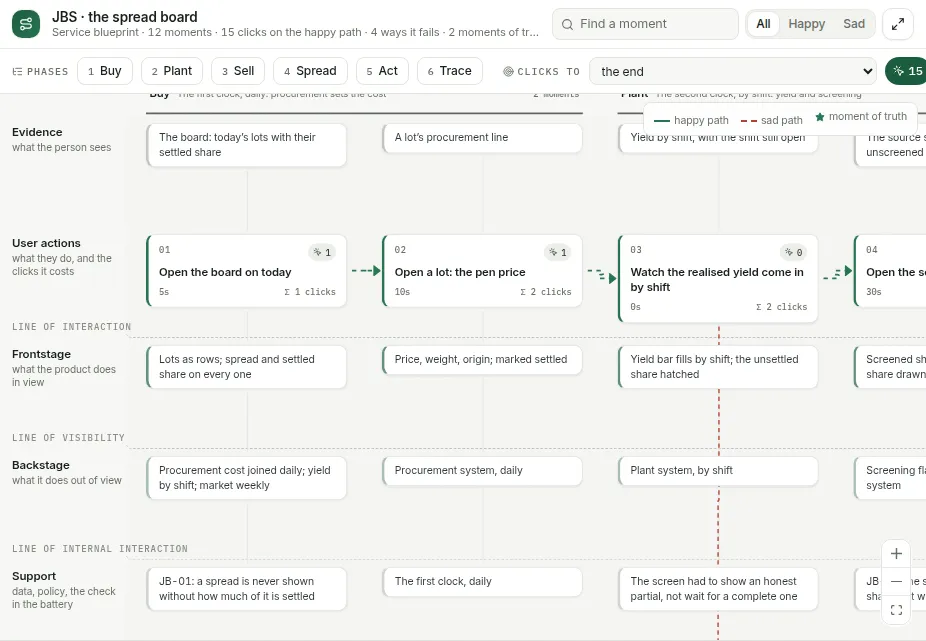
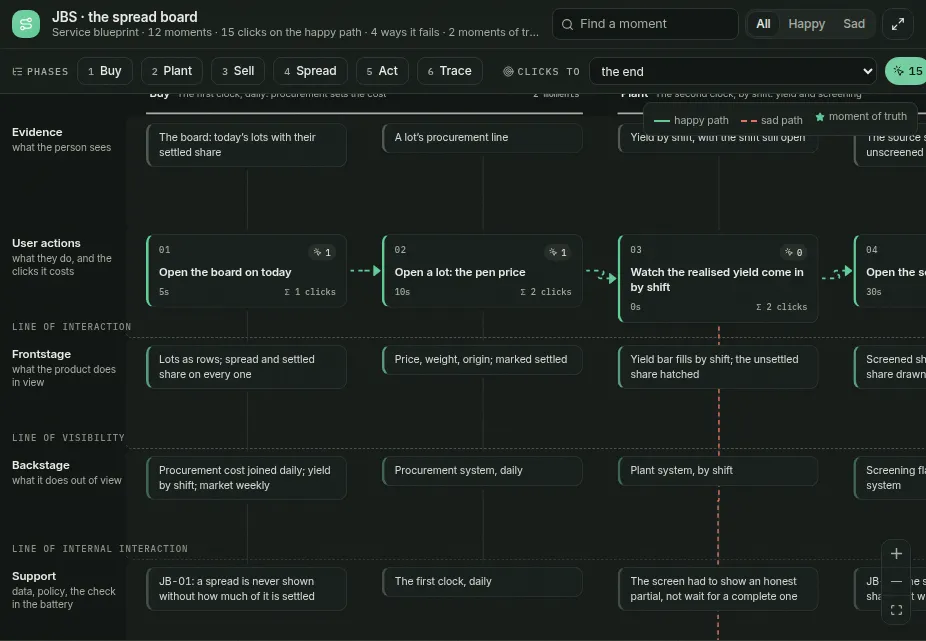
The spread board works on a phone, with the inspector as a sheet. Open it full screen for the whole board.
Open the board ↗Transcript
- 0:00 The rebuilt spread board, with fictional data, following one lot from the pen to the port.
- 0:03 Destination A’s export approval is pulled: its cuts re-route to the domestic market and the spread on the lot falls.
- 0:06 Restored, and the spread comes back.
- 0:08 Every lot through both plants in the last fortnight, with its spread as it stands and how much of it is settled.
- 0:11 How the spread assembles: what was paid for the lot, what it realised, and the gap between them.
- 0:14 Ten working days of realised yield against plan, shift by shift. The board can say where to look, not why.
- I owned
- The design of the spread board, as lead product designer at Astrato; this file rebuilds it with fictional data
- With
- Astrato’s delivery pods, as their one designer
- Theirs
- The client’s systems and the delivery team’s build; their roles are not part of this reconstruction, so none is claimed here
- Constraints
- Three systems on three clocks that could not see each other, and a net margin of about 2.3%, at which a point of yield is not a rounding error
- Friction
- The export gate was tracked by people who did not own the spread, so a market shutting mid-lot read as a bad week
Three systems on three clocks, drawn as one line
Before the board: the business end to end from the pen to the port, the gate an approval can shut, the targets a two per cent margin sets for the rebuild, the evidence under each decision, and the spec checked before every release.
Read this plate as text
The business drawn as five stations on one line: procurement on a daily clock, the plant on a shift clock, the markets on a weekly clock, the spread board and the plant controller. Between the plant and the markets sits the export approvals gate, per destination and pullable. A return leg says a pulled approval redirects the share to the domestic market and the board says so on the spread.
The gate is the part that was in the wrong department. Export approvals were tracked as a compliance list by people who did not own the spread, so a market shutting mid-lot showed up as a bad week at a plant. On this line the gate sits between the plant and the markets, where it actually is, and pulling it moves the share on the board the moment it is pulled.
The board is the fourth station, not the first, for the same reason the Novo cockpit is: it reads the three systems, it does not replace them. What it adds is the honest partial, a spread that is still forming with its settled proportion attached, which is worth more than a complete number that arrives after the decision it should have informed.
Read this plate as text
A tree with one root and four branches, all design targets rather than measured results. The root is the public 2.3 per cent net margin that sets the tolerance. The branches: no spread shown without its settled proportion, four destinations with a live approval switch, a model keyed on cut and market, and every figure opening to its query.
Read this plate as text
Four rows, each running input to finding to decision. The public 2.3 per cent margin forced the rule of no rounding and no smoothing. Three systems on three clocks forced showing the spread while it forms with a settled proportion. A representative plant controller, labelled as a pattern rather than an interview, forced every figure to open to its query. About 190 export countries, with approvals held in another department, forced the approvals onto the board, per destination and pullable.
The spec below holds the rebuilt board to six statements, each written as an acceptance test before the screens were rebuilt, and each verified by a check that runs before every release of this site, named in the right-hand column. It is the only kind of claim this file makes about the product: not that it was adopted, but that it satisfies these sentences, and that something other than my eye confirms it.
JB-01A spread is never shown without how much of it is settled.
Given any lot, when the spread is on screen, then the settled proportion is beside it, and the scenario sheet shows the break-even yield for the rest.
The spread sheet and the scenario sheet of the running board.THE PRODUCT, EVERY LOT
JB-02Pulling an approval redirects the share and flags the spread, in one act.
Given a lot in flow, when Destination A’s approval is pulled, then the flow says the approval was pulled, Domestic shows the redirected share and the allocation restates.
The checks “pulling A says so and flags the spread”, “Domestic shows the redirected 34%” and “allocation shows Domestic at 53%”.THE INTERACTION SUITE, RUN BEFORE EVERY RELEASE OF THIS SITE
JB-03Every figure opens to a query that names its lot.
Given the inspector, when the lot changes, then the generated query names the new lot and the bar names the lot’s plant.
The checks “changing lot recompiles the query” and “the bar names the lot’s plant”.THE INTERACTION SUITE, RUN BEFORE EVERY RELEASE OF THIS SITE
JB-04The source sheet draws the share that was not screened, rather than hiding it.
Given the Source sheet, when it opens, then the unscreened share is drawn and labelled as such.
The check “the source sheet draws the unscreened share”.THE INTERACTION SUITE, RUN BEFORE EVERY RELEASE OF THIS SITE
JB-05A shut route differs from a live one without motion.
Given reduced motion, when an approval is pulled, then exactly one route is dashed and thinner, and another has thickened to absorb the share.
The canvas check over the flow, which runs the board with motion off.THE CANVAS CHECK, RUN BEFORE EVERY RELEASE OF THIS SITE
JB-06The board works on a phone.
Given a 390-pixel viewport, when any sheet opens, then four tabs are on screen and nothing scrolls sideways.
The check “jbs phone: 4 bottom tabs, no sideways scroll, no errors”.THE INTERACTION SUITE, RUN BEFORE EVERY RELEASE OF THIS SITE
Four hundred billion through the door. Nine billion stays.
JBS reported net revenue of BRL 416.9bn for 2024, about USD 77.2bn, and net profit of BRL 9.6bn. That is a net margin of roughly 2.3%. Around 270,000 people, selling to more than 300,000 customers in about 190 countries.
Read this plate as text
Net revenue of BRL 416.9bn drawn as a full-width bar. Underneath, net profit of BRL 9.6bn drawn to the same scale, a sliver about one fortieth of the width. At a net margin of 2.3 per cent, a one per cent error in realised yield is worth a large fraction of the profit, which makes measurement precision at the plant a commercial question rather than an operational one.
This is a spread business. You buy an animal at a price set by a commodity market you do not control, you convert it into cuts at a yield set by your own plants, and you sell those cuts into markets whose prices and import rules you also do not control. What you keep is the difference, and the difference is thin.
Everything on this page follows from that. A reporting layer for a 41% margin business can afford to be approximate and directional. A reporting layer for a 2.3% margin business cannot, because the entire profit sits inside the error bars of a careless chart.

Three decisions, three systems, three different clocks
The spread on a lot is set by three separate decisions taken by three separate groups of people, recorded in three separate systems, on three separate time bases. By the time they can be reconciled, the lot is closed and the money is already made or lost.
"We know the margin. We know it on Thursday." THE SENTENCE THE PROJECT WAS BUILT AGAINST
Read this plate as text
Three decisions along a timeline. Procurement buys cattle against a regional index, known at purchase. The plant realises a yield, known after the shift. The commercial team sells cuts into destination markets, known when booked, which can be weeks later. The spread is the third minus the first, adjusted by the second, so it cannot be complete until the last cut is sold. The screen had to show an honest partial rather than wait for a complete one.
So the central object on the board is not a margin figure. It is a spread that knows how finished it is. Every lot carries a settled proportion: how much of its value has actually been sold against how much is still inventory being valued at an assumption. A lot that is 40% settled and a lot that is 95% settled are not the same claim, and showing them as two bars of the same colour is the error the old reporting made.

Transcript
- 0:00 One lot on the spread board, every export approval held.
- 0:01 Destination A’s approval is pulled: its cuts re-route to the domestic market and the spread falls from 1.3 to minus 6.9.
- 0:04 The approval comes back, and so does the spread.
Each chart, and what it has to say
A chart is chosen by the relationship it has to show, in the categories of the Financial Times’ Visual Vocabulary. In the rebuild every mark reads at 3:1 against its card or carries its value in print, so no number depends on telling two colours apart.
| Chart | What it has to show | The form, and why |
|---|---|---|
| How the spread assembles | Magnitude, and the gap between two of them: the price paid, what the lot realised, and the spread that is their difference | Three bars on one scale, each labelled, the spread coloured and signed by direction |
| Settled, not estimated | Part-to-whole: one share of the lot | A single ring with the figure printed beside it; the ring is drawn, the number is read |
| Yield by shift | Deviation from the plan | Columns against a dashed plan line, each with its value |
| Realised yield at the plant | Change over time, against the plan | One line per shift with the plan dashed across it, so a drift shows as a gap that opens |
| Two spreads, one lot | Magnitude: as it stands against your inputs | Two horizontal bars on one scale, each labelled |
There is no such thing as the price of beef
One animal does not become one product. It becomes dozens of cuts, and those cuts leave for different countries, under different certifications, at prices that have nothing to do with each other. The grain of the data is the cut and the destination, not the animal.
Read this plate as text
One carcass splits into four streams of cuts, each going to a different destination market with its own certification requirement that the producing plant must hold. The destinations are drawn at different heights because their prices are unrelated. If a plant loses an approval the cuts do not vanish, they sell into a lower-priced market instead, so a certification event is a margin event.
That is the modelling decision the whole board rests on. The old reporting keyed on plant and period, because that is how the plants are managed. The board keys on cut and destination, because that is where the money is decided, and rolls up to plant and period from there. It sounds like a technicality. It is the difference between a screen that tells you a plant had a bad week and a screen that tells you which market closed.

The supplier you buy from is not the only supplier
Sourcing compliance in Brazilian beef is a live and public issue for this company, and it is genuinely a data problem rather than a policy one. The difficulty is not screening the farm you bought from. It is the farm that sold to that farm.

Read this plate as text
A direct supplier sells cattle to the plant and can be screened, because the plant has its details. Behind that supplier sit indirect suppliers, the farms that raised or traded the animal earlier, with which the plant has no commercial relationship. Screening is strong at the direct tier and weak behind it, so the board shows coverage as a proportion with the unscreened share drawn rather than omitted. A tick would imply the whole chain was checked.
The plant manager already had a better number
As with the other engagement on this platform, the people closest to the operation had already solved their own version of the problem, and the reporting layer's job was to stop them each solving it differently.
I will say about research here only what a reconstruction can honestly support. The recurring finding in this kind of work, and the one that shaped the board, is that operational people do not distrust dashboards because the dashboards are ugly. They distrust them because they have been burned by a number that moved without explanation, and they have each built a private spreadsheet whose provenance they can personally vouch for.
A central board does not win that argument by being prettier. It wins it by being auditable: every figure can be opened to the query that produced it, every definition is stated where it is used rather than in a glossary nobody opens, and every number that changed since last week can say what changed it.

From the pen to the port, and back into the price
The path a lot takes, and the two points where what happens physically changes what the lot is worth.
Read this plate as text
Six stages left to right: cattle bought on an index, processed at a plant and shift, realised yield recorded, cuts allocated to destination markets constrained by the plant's approvals, shipped under cold chain, and settled when the last cut is sold. The two marked stages, realised yield and allocation to market, are where a physical fact becomes a commercial one. The board shows the spread forming across all six rather than waiting for the sixth.
Five decisions, and what each one cost to hold
The design calls that carried weight on this file, each with the thing that forced it.

The realised spread on a lot could only be stated once every cut had been sold, which in practice meant a weekly number arriving after the decisions it should have informed.
The board shows a spread that is still forming, with a settled proportion attached: how much of the lot’s value is actually sold against how much is inventory held at an assumption.
A late complete number is worth less than an early honest partial, as long as the partial says how partial it is.
I was asked for confidence intervals on the unsettled portion.
A completion percentage instead of an interval.
An interval invites the reader to take the midpoint as the answer. A completion percentage makes them ask how much has happened, which is the question that actually has a knowable answer.
Reporting keyed on plant and period, because that is how plants are managed, so a bad week looked like a plant problem whatever had actually caused it.
The model keys on cut and destination and rolls up to plant and period from there.
Price is decided per cut per market. Keying anywhere coarser averages away the only dimension that explains the movement.
Export approvals were tracked as a compliance list in a different department from the one that owned the margin.
Approval status sits on the same screen as the spread, with the volume currently depending on each approval shown beside it.
An approval is a price. Keeping it on a compliance page means the commercial consequence of losing one is discovered rather than anticipated.
Sourcing compliance was presented as a tick, which could not distinguish between a chain that had been checked and one that could not be.
Coverage is shown as a proportion with the unscreened share drawn rather than omitted, separating direct from indirect suppliers.
Converting an open question into a green tick is the failure mode that matters most here, because it is the one that gets quoted externally.
Two per cent does not forgive a rounded chart
| It worked if | Result | Status |
|---|---|---|
| No spread appears without how settled it is | 0 spreads shown without a settled proportion | |
| A live approval visibly moves the route | 4 destinations with a live approval; pulling one redirects the share | |
| Readers adopt it and decide sooner | Not measured, so not claimed |
As on the Novo Nordisk file, every figure in that band is public and none of them is a result of this work. There is no adoption number and no efficiency claim on this page, because I cannot show you the measurement.
The design position I will defend is the one the margin forces. In a two per cent business, the conventional dashboard virtues are actively harmful. Rounding is harmful because the profit lives inside the rounding. Smoothing is harmful because the variance is the signal. A single headline number is harmful because it averages across cuts and markets that have nothing to do with each other. Almost every default a charting library gives you is tuned for a business with room to be approximate, and this is not one.
What I would tell another designer taking this on: find out what the margin is before you design anything. It is a single number and it silently sets the tolerance for every decision you are about to make. At forty per cent you are designing for comprehension. At two per cent you are designing for precision, and those are not the same brief wearing different clothes.

What I would do differently
- Find who owns each input before drawing the screen. The export gate was tracked as a compliance list by people who did not own the spread, so a market shutting mid-lot showed up as a bad week.
- Agree targets with a way to measure them. This file sets targets, not results, because no adoption was recorded. The targets should have come with their measurement.
Source notes
- This case file is a reconstruction. The engagement was real and was delivered on Astrato, the Snowflake-native platform described in case file 002. The delivered artefacts, screens and results are covered by confidentiality and are not shown here. The problems on this page are real and public, the design decisions are the ones I argue for in this situation, and the screens were rebuilt for this site rather than exported from the work.
- No figure on this page is a measured project outcome. Nothing claims an adoption rate, a yield improvement or a margin gain, because that evidence cannot be shown.
- Company figures are from JBS S.A.'s published FY2024 reporting: net revenue BRL 416.9bn, about USD 77.2bn, up 14.6% in reais; net profit BRL 9.6bn, about USD 1.8bn. The 2.3% net margin is those two figures divided.
- Roughly 270,000 people, and more than 300,000 customers in approximately 190 countries, from JBS company reporting. Headcount figures differ between sources, with 270,000 and 280,000 both published; the lower figure is used here.
- The operational detail (three-clock spread formation, cut-and-destination grain, plant-level export approvals, direct against indirect supplier screening) is how this industry works and is not specific to any confidential material. Deforestation-free sourcing and indirect-supplier traceability are long-running public issues for Brazilian beef and for this company specifically.
- No per-plant, per-market or per-lot figure appears anywhere on this page or in the running product. The product uses fictional data throughout.
- The visual identity here is informed by the green that JBS's 2023 identity uses for sustainability, not copied from it. No logo, wordmark or trade dress is reproduced. JBS publishes no hex values for its current identity.